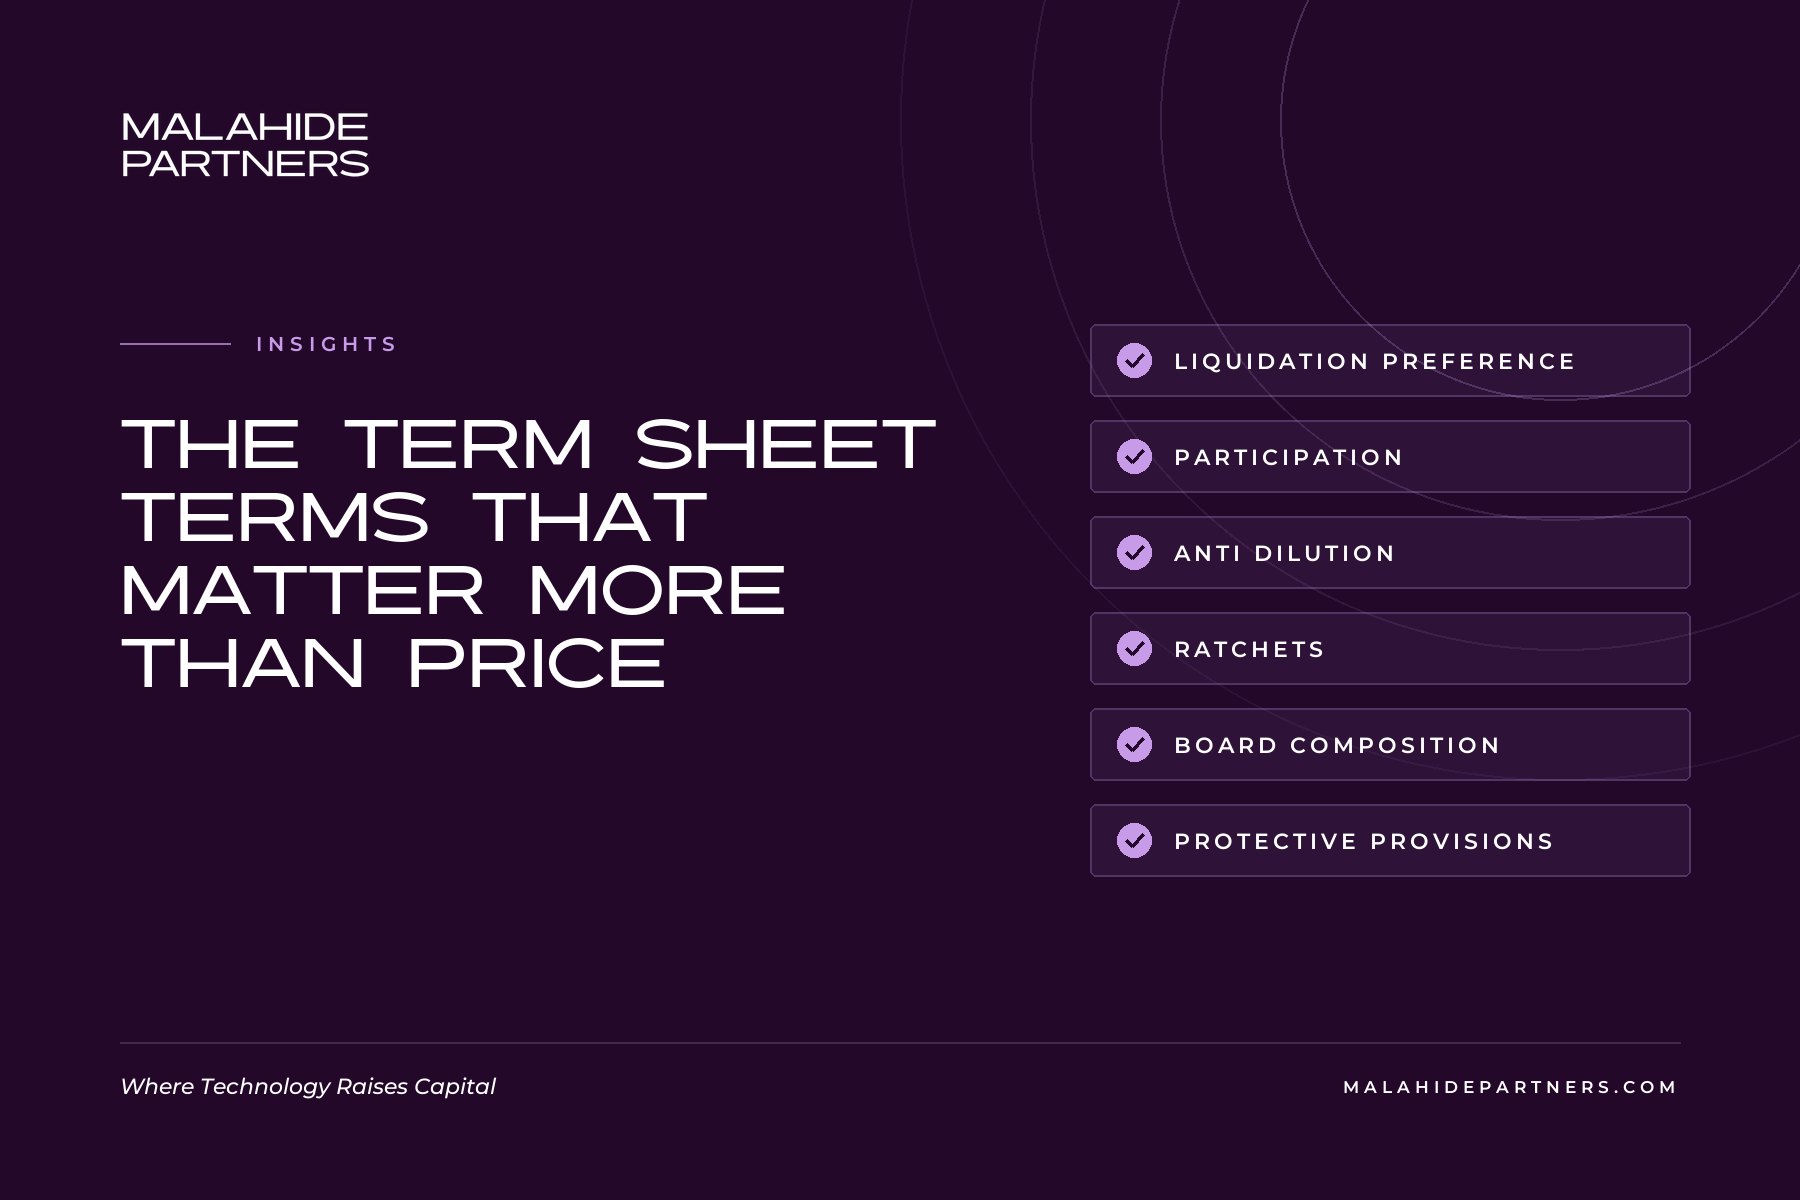
A term sheet is usually read from the top: the valuation, the round size, the dilution. The clauses further down decide who is paid first on a sale, who controls the board and what management can do without permission. For founders weighing competing offers, those terms often matter more than a few points on the headline price.
Why structure can outweigh price
Valuation is the easiest number to compare and the easiest to announce. It is also the number least likely to determine what founders and early shareholders actually receive. Two offers at the same price can produce very different outcomes in a modest exit, and an offer at a higher price can leave founders worse off if it carries heavier preferences or tighter controls.
The current market sharpens the point. Capital has concentrated at the very top: Sixteen billion dollar rounds absorbed $108.6 billion in Q2 2026, 53% of the quarter. Excluding the 16 largest rounds, Q2 2026 resembled a market of roughly $96 billion. Headline medians have also moved, and the Series A median post money valuation rose 37% year over year. When prices rise but investors remain selective, an investor who agrees to a demanding headline price may look for protection elsewhere in the document. The wider market data is set out in our Technology Capital Markets Review.
Liquidation preference
A liquidation preference gives preferred shareholders the right to receive their investment back before ordinary shareholders on a sale, winding up or other defined liquidity event. The common market position in venture rounds is a non participating preference equal to the amount invested, and that is a reasonable starting point.
The detail is where outcomes change:
- Multiple. A preference set at more than the amount invested means investors take a larger slice before anyone else is paid.
- Seniority. Later investors may ask to rank ahead of earlier ones, creating a stack. Pari passu treatment, where all preferred classes rank equally, is simpler and usually fairer.
- Definition of liquidation. Check whether a merger, an asset sale or a change of control triggers the preference.
- Dividends. Accruing dividends that add to the preference can quietly enlarge it every year.
The practical test is to model the waterfall at several exit values, including one below the post money valuation of the round. That is where preferences bite.
Participation
With a non participating preference, an investor chooses either to take the preference or to convert to ordinary shares and share in the proceeds pro rata, whichever pays more. With a participating preference, the investor takes the preference and then also shares in what remains. This is often described as a double dip.
Participation matters most in middle outcomes: a sale that is respectable but not spectacular. In those scenarios, a participating investor can take a materially larger share of proceeds than its ownership suggests, and founders and employees holding ordinary shares and options take less. Where participation cannot be avoided, a cap that ends participation once the investor has received a set return limits the damage.
Anti dilution
Anti dilution provisions protect investors if the company later raises money at a lower price per share. They adjust the conversion price of the investor's preferred shares, which in effect gives the investor additional shares at the expense of everyone else.
- Broad based weighted average is the prevailing norm. It adjusts the price according to both the new price and the number of new shares issued, measured against the whole capitalisation.
- Narrow based weighted average uses a smaller share count in the calculation and so produces a harsher adjustment.
- Full ratchet resets the investor's price to the new, lower price regardless of how few shares are issued. It is the most punitive form.
Check the carve outs too. Shares issued under the option pool, on conversion of existing instruments or in agreed strategic transactions should not trigger an adjustment. Some term sheets add pay to play provisions, under which investors who do not support a future round lose their protections. These can work in founders' favour.
Ratchets
Beyond anti dilution, ratchets appear in other forms, particularly in growth and pre IPO rounds. An IPO ratchet gives an investor extra shares if the company floats below an agreed price, guaranteeing a minimum return. Valuation or performance ratchets adjust ownership depending on whether the company hits revenue or other targets, and tranched rounds release capital only as milestones are met.
These structures let an investor agree a higher headline price while protecting its downside, which is exactly why they deserve scrutiny. Public markets now give late stage boards a credible dual track once revenue clears roughly $200 million. For companies approaching that point, an IPO ratchet agreed in a growth round can shape the economics of a listing years later. Model the ratchet against realistic, not optimistic, scenarios.
A higher valuation bought with heavier preferences, ratchets or vetoes is not a higher valuation. It is a different deal, and founders should price it as one.
Board composition
The board appoints and removes the chief executive, approves budgets and decides on sales and financings. Who sits on it matters more over the life of a company than almost any economic term.
Early boards are usually founder controlled. As rounds accumulate, investors take seats and control can shift without any single round appearing decisive. Look at the board the term sheet creates, and also at the board likely to exist after the next round, when the new lead will expect a seat of its own. Independent directors, agreed jointly by founders and investors, are often the most useful balancing mechanism. Observer rights should be limited and subject to confidentiality.
Founders preparing for an institutional round should think about board structure early, as part of wider Series A readiness.
Protective provisions
Protective provisions give preferred shareholders a veto over specified decisions. Some are standard and reasonable: issuing shares that rank ahead of existing preferred, changing the rights attached to their shares, or approving a sale of the company.
Others reach into operations: approval of annual budgets, hiring senior staff, taking on debt above a threshold or entering material contracts. These are worth negotiating carefully. A debt veto, for example, matters if venture debt is part of the plan, and venture debt used as a round complement is typically sized at 20% to 35% of an equity round. The voting threshold matters as much as the list. A vote of the preferred as a single class is usually workable. Separate series votes can give a small investor a blocking position over decisions that the rest of the cap table supports.
How to prioritise in negotiation
Few founders win every point, and trying to can cost goodwill and time. A sensible order of priority is usually: board control, the liquidation preference and participation, anti dilution, protective provisions, and then secondary terms such as information rights, drag along thresholds and founder vesting.
- Model every offer. Compare proceeds to founders and employees across a range of exits, not just the headline price.
- Think about precedent. Terms agreed now tend to become the floor for every later investor.
- Be willing to trade. A slightly lower price with clean terms is often worth more than a higher one with heavy structure.
- Use experienced counsel. Many of these terms look standard in summary and only reveal their effect in the long form documents.
How Malahide Partners helps
We advise technology companies raising between $1M and $100M on structuring and negotiating rounds, from the first conversations with investors to the final documents. Our equity advisory work includes modelling competing term sheets, identifying which terms deserve a fight and keeping a process competitive so that founders negotiate from strength. Where a round sits alongside a sale process or wider strategic decisions, our strategic advisory team supports the board directly. If you are reviewing a term sheet or preparing to raise, book a call.
Frequently asked questions
What term sheet terms matter more than valuation?
Liquidation preference, participation, anti dilution protection, ratchets, board composition and protective provisions often matter more than headline price. Together they decide who is paid first on an exit and who controls key decisions.
What is a non participating liquidation preference?
It gives investors the choice of either receiving their investment back first or converting to ordinary shares and sharing proceeds pro rata, whichever pays more. It is the common market standard in venture rounds and is generally fairer to founders than participating preferred.
What is the difference between full ratchet and weighted average anti dilution?
Full ratchet resets an investor's price to any lower future price, regardless of how many shares are issued. Broad based weighted average adjusts the price in proportion to the size of the new issue, which is milder and is the prevailing norm.
Why do protective provisions matter to founders?
They give investors veto rights over decisions such as new share issues, sales, debt and sometimes budgets. Broad operational vetoes or separate series votes can let a single investor block decisions the rest of the company supports.
About Malahide Partners. Malahide Partners is a capital advisory firm serving technology companies exclusively, headquartered at 124 City Road, London. The firm advises founders, boards and sponsors on equity and debt raises between $1M and $100M and on M&A, working with family offices, funds and institutional investors across Europe, the GCC and North America. Malahide Partners represents the company and runs the process end to end; it is not an investor or a fund manager.
Media enquiries. enquiries@malahidepartners.com
Sources. Crunchbase data, July 2026, as cited in the Malahide Partners H1 2026 Technology Capital Markets Review; Malahide Partners, H1 2026 Technology Capital Markets Review; Carta, State of Private Markets, as cited in the Malahide Partners H1 2026 Technology Capital Markets Review.